Option 1Chattel mortgage
Best forMost tradies and operators
Who owns itYou, from day one. The lender registers its interest
Good to knowOnce the final payment is made, it is yours outright
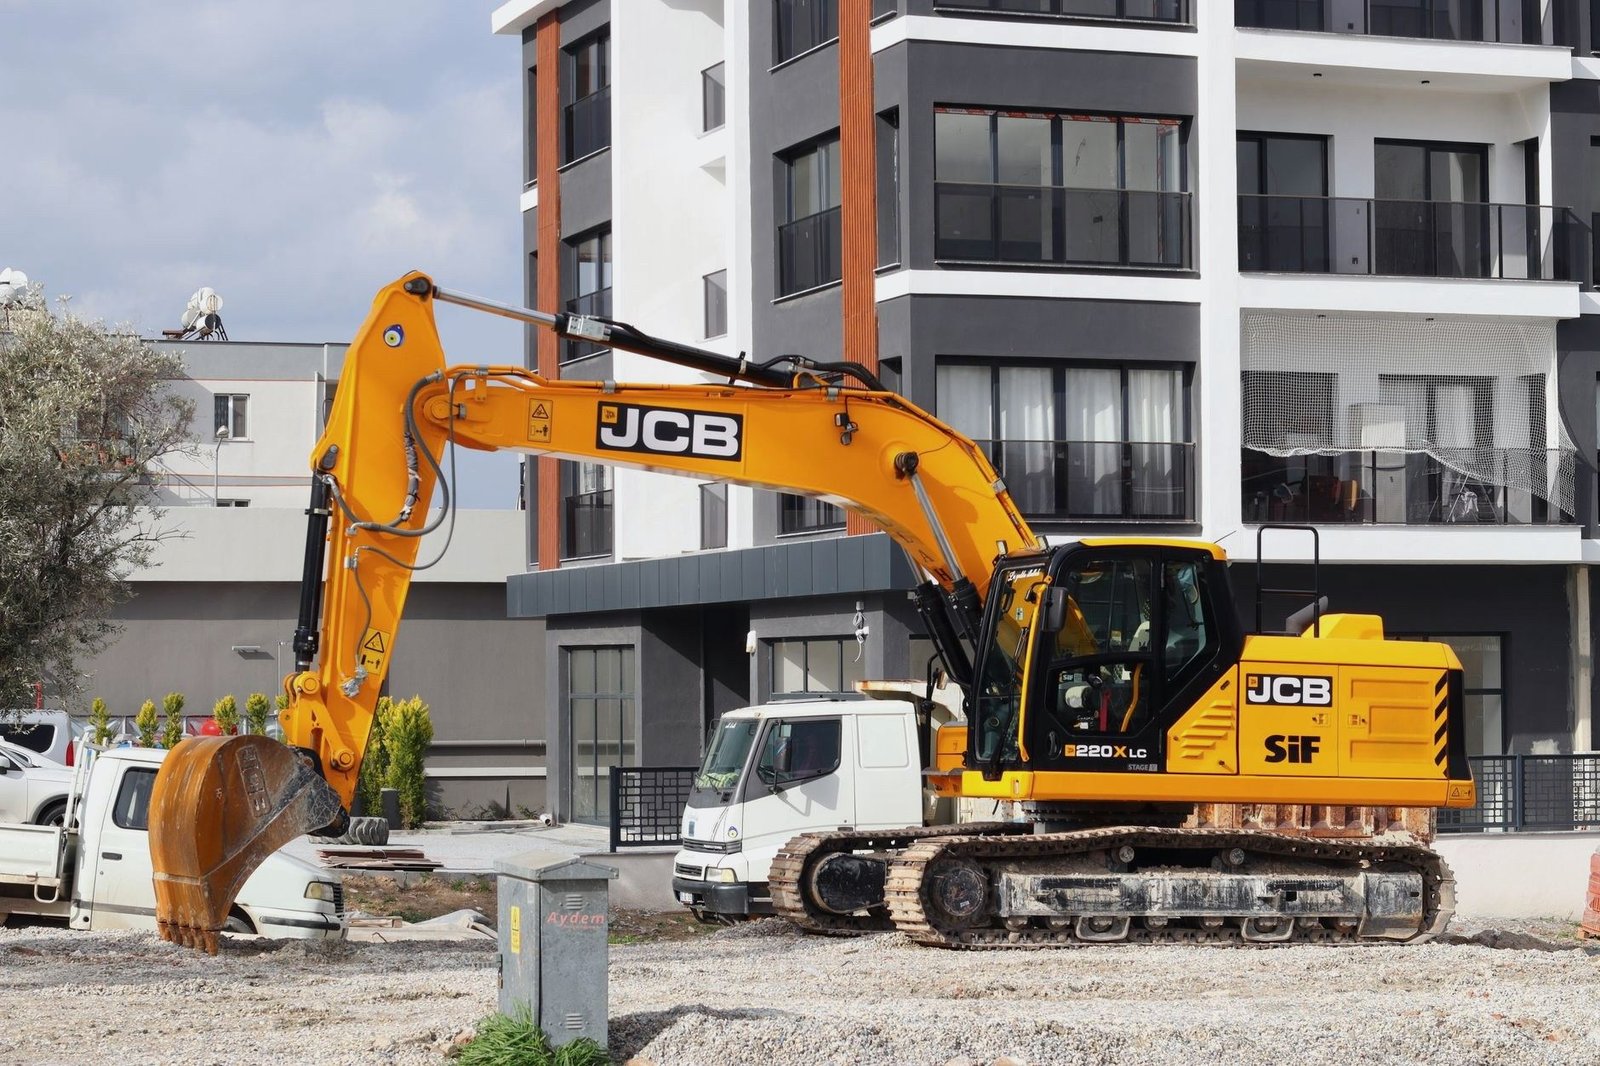
Yellow goods, plant, trucks and workshop assets, without draining working capital. One enquiry, 30+ lenders compared.
If your business uses it to earn income, there is usually a lender on our panel that will fund it.
We match the machine and its age to the right lender, run PPSR and ownership checks on private and auction buys, work to the auction house's timelines, and lodge the application, chase the lender and settle.
Get ApprovedPick the one that fits. The paperwork changes, the process does not.
The simplest path. Invoicing is clean, most lenders settle quickly, and the dealer handles delivery.
Talk to us before auction day so you know your position and can bid with a firm limit. Auction houses want settlement fast, and we work to their timelines.
Plenty of good machines change hands owner to owner. Lenders need a PPSR search, proof of ownership and sometimes an inspection, and we organise all of it.
Newer ABNs and ABN holders without current financials can still have options with the right lender.
More on low doc business finance
Most equipment is financed one of three ways. Here is how they compare.
Best forMost tradies and operators
Who owns itYou, from day one. The lender registers its interest
Good to knowOnce the final payment is made, it is yours outright
Best forBusinesses that would rather pay to use the gear
Who owns itThe financier, sometimes with an option to buy at the end
Good to knowYour accountant is the person to confirm it suits your business
Best forABN holders without current financials
Who owns itDepends on the structure. Low doc changes the paperwork, not the ownership
Good to knowLess paperwork, not none. Expect ABN history and bank statements
Which structure suits you can depend on your tax position, so check with your accountant. We arrange finance, we do not give tax advice.
Get ApprovedMove the sliders to see roughly what repayments could look like. When you enquire, we compare real lender options for your situation.
Indicative estimate only. The rate is an example you choose, not a rate we are offering. Actual repayments vary by credit profile, lender, fees and product type, and this is not a quote or an offer of credit.
You do not need a full set of financials to get started. If you hold an ABN and your paperwork is not current, ask us about low doc business finance. Plenty of our clients are sole traders and small operators caught between tax returns.
Tell us about the gear and your business. This does not affect your credit score.
We check your position against lender criteria before anything is lodged, so you know where you stand first.
We match your deal to lenders that suit the machine, its age and your paperwork.
Once your documents are in, approvals often land within 24 to 48 hours, subject to lender criteria and credit assessment.
Ready to price up that machine? Start your enquiry and we will take it from there.
We work with clients and lenders right across Australia. As a credit representative under AFAS Group's Australian Credit Licence, we're held to strict compliance and professional standards.
Quick answers and updates at every step. Your time is money and we don't waste it.
CR No. 576829 under AFAS Group ACL 414426. FBAA M-362098. AFCA 121188.
Self-employed, adverse credit, new ABN, specialist assets. Our lender relationships are built for it.
We work for you, not the lender. Straight about your options, the fees and the best path forward.
Highly recommend Solvyr Capital. They helped me with finance for my car and made the whole process very quick and easy. Very professional, easy to communicate with, and everything was explained clearly. Great broker and great service. Thank you!
Highly recommend!! Wouldn't go anywhere else. Super efficient, professional service.
Had a great experience with Nash, very friendly extremely helpful was super good process getting my loan with Solvyr
The longer read, for when you want the full picture. Tap a topic to open it.
If your business uses it to earn income, there is usually a lender on our panel willing to finance it. We arrange equipment and machinery finance through a panel of more than 30 lenders, from the big banks to specialist non-bank funders. That matters, because no single lender suits every machine or every business. We are not trying to squeeze your deal into one lender's box.
The gear we finance most often:
Need a ute or van to go with the machine? That side of things is covered on our car finance page.
Most equipment finance in Australia is written as a chattel mortgage. You own the machine from day one, the lender registers its interest over it, and once the final payment is made it is yours outright. Simple, and it suits most tradies and operators.
Rental and lease structures work differently. The financier owns the equipment and you pay to use it, sometimes with an option to buy at the end. The right structure depends on your circumstances, so your accountant is the person to confirm what suits your business.
Which structure works out better for you depends on your tax position, and that is a question for your accountant, not your broker. We do not give tax advice. What we do is find lenders that offer the structure your accountant recommends, then compare what is on the table.
Where you buy matters less than people think. We arrange finance for equipment from all three channels:
Machine age and hours affect which lenders will take the deal. This is exactly where a broad panel earns its keep. If one lender caps machine age at a level that rules out your excavator, another on our panel probably will not.
Tell us what you are looking to finance and get a straight answer. The enquiry does not affect your credit score.
Get ApprovedOften, yes. Several lenders on our panel offer low doc options for ABN holders, which means far less paperwork than a full doc application. Approval still depends on lender criteria and a credit assessment, but not having your latest tax return done does not rule you out.
Once your documents are in, approvals often land within 24 to 48 hours. The initial enquiry itself takes about two minutes. Exact timing depends on the lender, the machine and how quickly the seller provides paperwork, and every approval is subject to lender criteria and credit assessment.
Usually, yes. Lenders finance auction and private sale machines every day, subject to their criteria and a credit assessment; they just require extra checks such as a PPSR search and proof of ownership. For auctions, talk to your broker before bidding so you know where you stand and can settle within the auction house's timeframe.
With a chattel mortgage you own the equipment from day one and the lender holds security over it until the loan is paid out. With a lease or rental, the financier owns the gear and you pay to use it, sometimes with an option to buy later. Which structure suits you comes down to your tax and business setup, so talk to your accountant before deciding.
The initial enquiry with us does not affect your credit score. We assess your position and match you with suitable lenders first, and the initial enquiry does not affect your credit score, and a credit check only happens later once you choose a lender and give us the go-ahead. That way one machine purchase does not leave a trail of enquiries on your file.
Tell us what you are looking to finance. It takes about two minutes and does not affect your credit score.
Prefer to talk? Call 0468 157 797